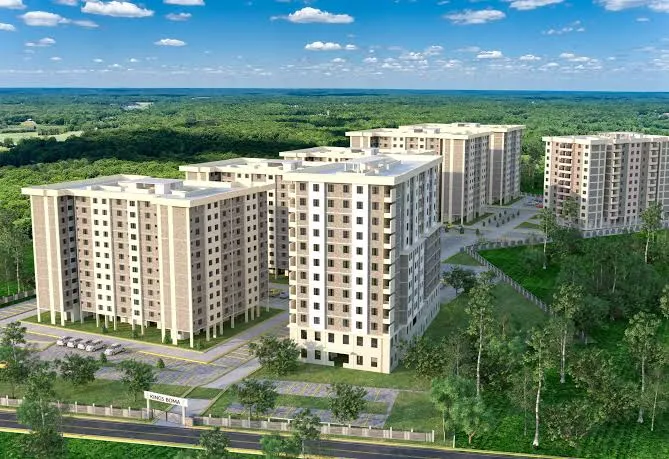
Kenya’s Affordable Housing Programme was conceived as one of the country’s most ambitious attempts to put decent homes within the reach of ordinary citizens.
But behind the cranes, construction sites, and promises of new estates lies a much less visible question: Who will ultimately pay for the housing programme if the money committed to it is substantially greater than the money collected to finance it?
A fiscal-risk assessment contained in an intelligence and risk-analysis brief raises precisely that question.
Its central concern is stark. The programme is associated with a project pipeline estimated at about KSh1.8 trillion, while approximately KSh205 billion has reportedly been collected through the housing levy. On the figures presented in the assessment, that leaves a potential financing gap of roughly KSh1.59 trillion—about 88.6 per cent of the stated programme requirement.
Those numbers do not, by themselves, establish that the entire difference represents an immediate government debt. Nor is the assessment an official government audit. But they illuminate a potentially consequential fiscal question: how were projects of such magnitude to be financed, and what happens when the expected revenue does not keep pace with the commitments?
A housing programme with a financing problem
The danger in infrastructure programmes is not always visible at the point where a building rises from the ground.
A project can look successful while the financial obligations behind it accumulate.
Contractors mobilise equipment. Workers are hired. Materials are purchased. Consultants undertake professional work. Banks extend credit. Government agencies certify work.
But somewhere in that chain, somebody must eventually pay.
The assessment warns that the Affordable Housing Programme may have moved considerably faster on the construction and contracting side than on the revenue side.
It identifies 176 stalled projects, raising concerns over unpaid or deferred claims involving contractors, consultants and other professionals.
If such claims continue to accumulate, the financial problem can move from the construction site into the banking sector, courts and ultimately the national budget.
That is where the housing programme becomes more than a question of houses.
It becomes a question of public finance.
When contractors become the financiers
There is another side to delayed government payments that is often overlooked.
When a contractor is not paid promptly, the project does not necessarily stop immediately. The contractor may continue working using working capital, supplier credit or commercial bank financing.
For a while, the construction site may continue to look normal.
But the financial pressure is being transferred elsewhere.
A contractor with several unpaid certificates may eventually find it difficult to pay workers, suppliers and lenders. A bank exposed to several contractors facing delayed payments may also begin reassessing its risk.
The result can become a chain reaction:
government payment delays → contractor cash-flow pressure → bank exposure → stalled projects → contractual claims → higher eventual public cost.
This is why the report's warning about contractor insolvency deserves attention.
The issue is not merely whether a particular contractor gets paid late. It is whether a large number of contractors can withstand prolonged delays without the financial stress spreading through the construction and banking sectors.
The taxpayer may eventually enter the picture
The most important question is what happens if housing-levy revenues cannot support the contractual obligations already created.
There are several possible routes.
The State could restructure projects. It could slow the pipeline. It could renegotiate contracts. It could seek alternative financing. It could increase allocations from ordinary government revenues.
Or, depending on the legal and contractual circumstances, the State could face claims arising from delayed or terminated projects.
Each route has consequences.
If additional money has to come from the national budget, resources that could otherwise finance health, education, agriculture, security or other public programmes could face competing demands.
If borrowing is used, the issue becomes one of public debt.
And if contracts generate arbitration, litigation, interest or compensation claims, the eventual cost may be higher than the original construction bill.
This is the meaning of a fiscal-risk assessment: a commitment can become a liability even before the money appears in the national budget.
The unfinished building is itself a liability
There is also a physical dimension to the financial risk.
A stalled housing project is not simply a project waiting for money.
Construction materials deteriorate. Completed structures may require protection. Sites can become vulnerable to vandalism. Security costs can accumulate. Restarting construction after a prolonged interruption may cost more than continuing construction without interruption.
Inflation can also change the economics of the original contract.
A building that was affordable to complete when it was tendered may require considerably more money after months or years of delay.
Thus, the longer a financially troubled project remains unfinished, the possibility of additional costs increases.
The paradox is obvious: a programme intended to make housing more affordable could become more expensive if financial controls and sequencing fail.
Were commitments made before the money was secured?
Perhaps the most fundamental question raised by the assessment concerns project approval.
Large public construction programmes normally require careful consideration of available financing, project feasibility, quantities, costs, contractual obligations and future cash flows.
The assessment questions whether those considerations were sufficiently aligned with the number and scale of projects that entered the pipeline.
That question deserves a factual answer rather than political rhetoric.
For every major project, the public should be able to understand:
What was the approved project cost?
What source of financing was identified?
How much has actually been paid?
How much remains outstanding?
What work has been certified?
How many projects have stalled?
What contractual liabilities have been created?
What exposure do commercial banks have?
What is the expected source of funds for completing each project?
Those questions are particularly important when the difference between the reported programme pipeline and levy collections runs into trillions of shillings.
The 2027 factor
The approach of the 2027 General Election adds another layer of uncertainty.
Large infrastructure programmes inevitably become part of the political conversation during election periods. But fiscal commitments do not disappear when political priorities change.
A contractor awaiting payment cannot pay a bank loan with political promises.
A bank cannot classify an unpaid government certificate as settled simply because a project is politically important.
And the taxpayer cannot be insulated indefinitely from liabilities that have already been contractually created.
The critical issue, therefore, is continuity of financing and transparent management of existing commitments.
If projects are started, they must either have a credible financing path to completion or be subjected to an orderly review before further resources are committed.
The uncomfortable arithmetic
The most striking feature of the assessment is ultimately the arithmetic.
A programme associated with approximately KSh1.8 trillion in projects cannot safely be assessed only by counting houses under construction.
It must also be assessed by counting the obligations behind those houses.
The approximately KSh205 billion reportedly collected through the housing levy is substantial money. But when placed against a KSh1.8 trillion project pipeline, it raises a basic public-finance question about the sustainability of the model.
That does not necessarily mean that every shilling of the difference is an unfunded liability. The financing architecture of the programme may involve other sources, future revenues, private-sector participation and different contractual arrangements.
But precisely because those distinctions matter, the public deserves greater clarity.
What should happen now?
The assessment proposes measures that point toward a more cautious approach: reviewing the project pipeline, freezing projects that have not started, restructuring contracts where necessary, paying contractors for properly certified work and stress-testing banks exposed to the programme.
Most importantly, future commitments should be aligned with realistic revenue.
That principle is larger than the Affordable Housing Programme.
A government can announce a project today, but the bill may arrive years later.
Responsible fiscal management requires that policymakers consider not only the political and social benefits of a project, but also the future obligations it creates.
Kenya's housing challenge is real. So is the need for affordable and decent housing.
But the solution to a housing deficit cannot simply be to build faster.
It must also be to finance sustainably, contract responsibly and account transparently.
The real test of the Affordable Housing Programme may therefore not be how many houses can be announced, launched or photographed under construction.
It may ultimately be whether Kenya can complete what it has already committed to without turning today's housing ambition into tomorrow's fiscal burden.
And that is the trillion-shilling question the country can no longer afford to ignore.
No comments yet. Be the first to share your thoughts.